
“Work with Jakub on my new health insurance and it was smooth process.Thank you for all your knowledge”
Health insurance, explained by real people
Learn it here, or let a licensed advisor do the heavy lifting.
4.7 on Google · 61 reviews18 statesSince 2009
Find your best fit
No email needed
a year
Your best fit shows up herePick your answers above. Still to go: {{ todo }}.
Example answers. Change any of them to see yours.
How it works
Three steps with a licensed advisor.
Call a licensed advisor or get a quote online
Tell us who needs coverage, your ZIP code and your doctors.
We compare plans for you
A licensed advisor checks the plans available to you through us for your doctors, prescriptions and budget.
We help you enroll, then stay your advisor
We walk you through enrollment and are here for questions, renewals and changes all year.
4.7
“Jakub was knowledgeable, patient, and extremely helpful in guiding me to the best medical plan for me and my family. A pleasure to do business with—I’ll definitely return next year!”
“My experience was wonderful I was nicely explained to and I I understood everything about my insurance I really appreciate 🙏 Jakub you are good God bless you 🙏”
“Great experience!! Very knowledgeable about all health insurance options. Took the time to fine the plans that would work best for me !!”
“I had such a great experience with Jakub! He was incredibly kind, compassionate, and made sure I understood every detail. You can tell he genuinely loves helping people. He found the perfect plan for me and my son. Truly grateful! 😊”
“Jakub was a pleasure dealing with through the gauntlet of health insurance issues. He made everything clear and concise and made sure we understood our new policy. I highly recommend him.”
“I had the pleasure of working with Jakub Slomczewski and it was an amazing experience. He helped me get set up with health insurance for both me and my family and made the entire process so easy and stress-free. He explained everything clearly, answered all my questions with so much patience, and genuinely cared about finding the best option for me. It’s rare to meet someone who is both super knowledgeable and genuinely kind, but Kuba is exactly that.”
“I am a small business owner and Jakub has helped me navigate the very overwhelming healthcare system options provided. He walked me through best options for me ,step by step, and guided me to making a decision on best option. Thank you Jakub.”
“I’ve been assisted by Jakub for the last two years with my insurance and he has done a tremendous job of helping me find the best plans for my needs. I think he is very honest and straightforward which I greatly appreciate while navigating the confusing aspects of healthcare. Thanks so much!!”
“Just wanted to thank you Jakub Slomczewski for helping me to find the perfect healthcare plan for me.He was very nice and highly educated. He answered every question I had and explained everything thank you 🙏”
“Outstanding customer service! Very informative and professional. Entire set up process was a breeze. I would recommend this company for your health insurance needs.”
Licensed advisors who answer the phone
A family-run Chicago agency, helping people since 2009 and licensed in 18 states. We work for you, and it costs you nothing.
Meet our team
Team Lead · Certified Insurance Advisor
Certified Insurance Advisor
Certified Insurance Advisor
Certified Insurance Advisor
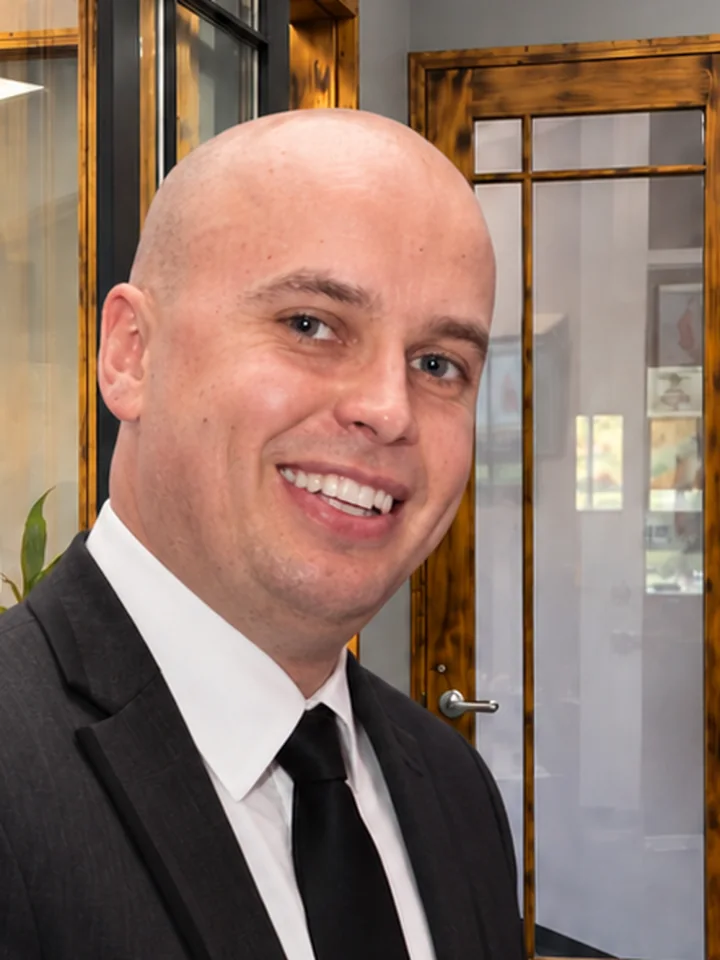
Certified Insurance Advisor
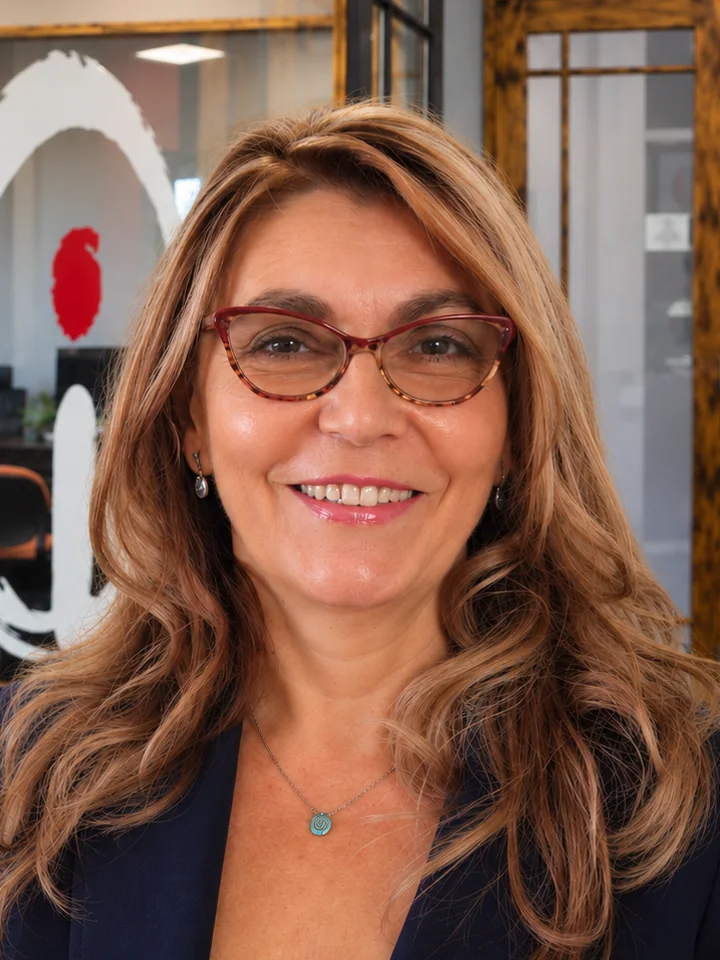
Certified Insurance Advisor
Plan types, explained
Every kind of health coverage we place, with what to keep in mind included.
Not sure which one fits? Compare every type of health insurance in one place.
Compare all plan types Marketplace (ACA) plansGood for: most people, especially if your income qualifies for a tax credit.Keep in mind: if you earn more than you estimate, you pay the extra credit back.Learn more
 Private health plansGood for: healthy people who earn too much for a credit.Keep in mind: not a Marketplace plan. It asks health questions and can turn you down.Learn more
 Short-term plansGood for: a gap of a few months between plans.Keep in mind: not ACA-compliant. Pre-existing conditions usually are not covered. Not sold in Illinois.Learn more
 Group plansGood for: business owners who want one plan for the team.Keep in mind: usually needs at least one employee besides the owner.Learn more
 Supplemental coverageGood for: anyone with a deductible: hospital indemnity, accident, critical illness, dental and vision.Keep in mind: works alongside a health plan, never instead of one. Hospital indemnity and critical illness policies are not health insurance coverage.Learn more
Obamacare Hotline and/or Medicare Po Polsku are private companies not affiliated with any local, state, or federal government agency.
What changed for 2027
Open enrollment starts November 1.
New Medicaid work rules in Illinois
In 2027, adults who aren’t eligible for Illinois Medicaid because they didn’t meet the new work rules can’t get Marketplace tax credits. People with an exemption aren’t affected by this rule.1
What to do if you get a noticeCigna and Molina are leaving Get Covered Illinois
Their 2026 plans end December 31. Members need to pick a new plan for 2027.2
Check my renewal letterHealthCare.gov deadline: December 15
On HealthCare.gov, pick a plan by December 15 for coverage that starts January 1. Open enrollment there runs November 1 to January 15, and plans chosen after December 15 start February 1. State marketplaces, like Get Covered Illinois, set their own dates.3
Out-of-pocket limits go up
The most a plan can make you pay in 2027 rises to $12,000 for one person.4
More coverage

Get my free quote
- 1Answer a few questions
Your situation first. Contact details come last. - 2A licensed advisor calls you
Within 24 hours. - 3We go through every option
With what to keep in mind on each one. It costs you nothing.
We never sell your information.
Questions people ask
Plain answers to what people ask us most. Tap a question to open it.
Visit the Learn libraryIs a short-term plan real health insurance?
Not in the way most people mean. Short-term plans are not ACA-compliant: they can ask health questions, usually do not cover pre-existing conditions, and do not have to cover every essential health benefit. They bridge a gap of a few months.
What is the 4× cliff, and does it affect me?
The extra tax credits ended with 2025, so the Marketplace tax credit now stops completely once household income goes above 4× the poverty line, and that continues for 2027 coverage. If you are close to that line, a careful income estimate matters, and a private plan may be worth comparing.
Do I have to report income changes during the year?
You should. Your credit is based on your estimate for the year. Report changes on your Marketplace account as they happen. If you earn more than you estimated, you may pay some or all of the extra credit back when you file taxes; if you earn less, you may get more back.
What is the difference between a deductible and an out-of-pocket maximum?
The deductible is what you pay for covered care before the plan starts sharing the cost. The out-of-pocket maximum is the most you pay in a year for covered in-network care, counting the deductible, copays and coinsurance. Once you reach it, the plan pays for covered in-network care for the rest of the year. Premiums do not count toward it.